The Future of Personal Finance in a Digital-First World
The relationship between individuals and their money is undergoing a profound reinvention. For generations, managing personal finances meant visiting a brick-and-mortar bank branch, balancing a physical checkbook, and waiting days for transactions to clear. Today, those methods feel like relics of a distant past. We are living in a digital-first world where smartphones, automated algorithms, and cloud networks form the primary interface for financial decision-making.
This shift is more than just a matter of convenience or replacing paper with pixels. The digitization of money is altering how people save, invest, borrow, and protect their wealth. As financial technology continues to accelerate, the future of personal finance promises unprecedented accessibility and efficiency, alongside entirely new responsibilities and risks for consumers.
The Rise of Agentic AI and Autonomous Money Management
Artificial intelligence has graduated from simple budgeting tools that categorize expenses after they occur. The future of personal finance is defined by agentic AI, which refers to autonomous systems capable of reasoning, making decisions, and executing multi-step financial workflows on behalf of a user.
Instead of a consumer manually logging into an app to transfer money into a savings account, autonomous finance systems monitor income, predictable bills, and variable spending patterns in real time. When the system detects a surplus of capital, it automatically optimizes those funds. It might direct a specific portion to a high-yield savings account, allocate another fraction to pay down high-interest debt, and route the remainder into a fractional stock portfolio based on the user risk tolerance.
This transitions personal finance from a reactive chore to an invisible, self-optimizing utility. Humans set the high-level goals and guardrails, while intelligent software handles the daily execution, effectively democratizing the benefits of personalized wealth management.
Open Banking and the Hyper-Personalization of Credit
Historically, traditional financial institutions held a monopoly on consumer financial data, keeping credit history, transaction records, and asset balances locked in isolated databases. The widespread adoption of Open Banking frameworks has dismantled these data silos.
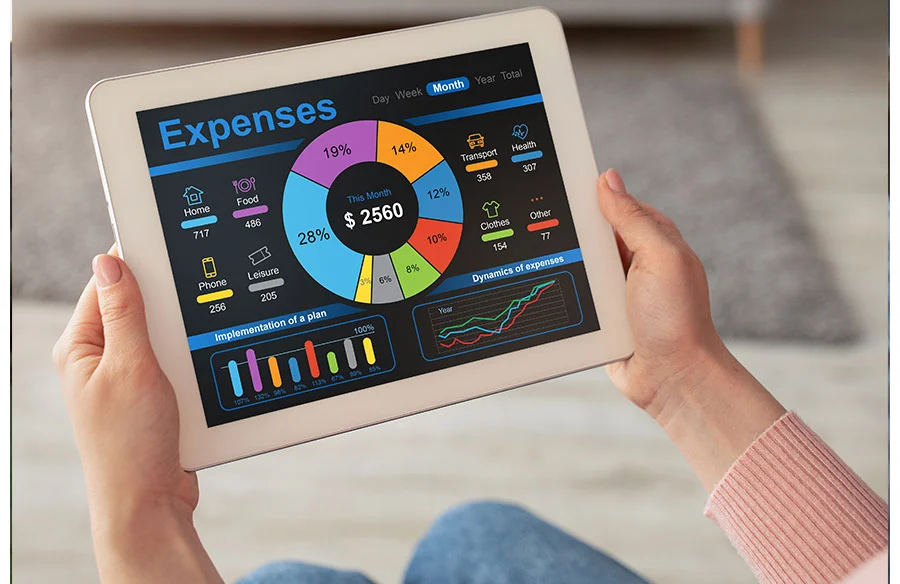
Through standardized Application Programming Interfaces, consumers can now securely grant third-party financial applications direct access to their banking data. This seamless flow of information enables a holistic, three-sixety-degree view of an individual financial health within a single dashboard.
For personal finance, the ultimate beneficiary of Open Banking is the personalization of credit and lending. Rather than relying strictly on a traditional credit score, which can be a slow, rigid metric, modern lenders utilize real-time cash flow data, utility bill payment history, and consistent saving habits to assess creditworthiness. This allows individuals with thin credit files to secure affordable financing, mortgages, and personal loans based on their current financial reality rather than historical omissions.
Embedded Finance and the Invisibility of Transactions
One of the most seamless trends in the digital economy is embedded finance, which integrates financial services directly into non-financial consumer platforms. Instead of navigating to a dedicated banking portal, financial choices are presented precisely at the point of need.
Consider ride-sharing applications, e-commerce marketplaces, or digital health platforms. The payment, insurance, or short-term financing option is woven directly into the checkout process. While this friction-free ecosystem provides incredible convenience, it poses a distinct psychological challenge for personal money management.
When the physical act of handing over cash or sliding a plastic card is removed from a transaction, the cognitive pain of paying is minimized. This frictionless spending environment makes it exceptionally easy for consumers to overextend themselves financially, increasing the need for digital budgeting systems that provide real-time friction, such as instant notifications showing how a purchase impacts a long-term financial goal.
Decentralized Finance and the Democratization of Yield
While traditional fintech optimizes the existing banking architecture, Decentralized Finance presents an entirely alternative financial ecosystem built on public blockchain networks and automated smart contracts.
Decentralized finance eliminates traditional intermediaries like corporate banks, brokerage firms, and clearinghouses, allowing individuals to engage in peer-to-peer lending, borrowing, and asset trading. For personal finance, this introduces unique opportunities to access global liquidity and generate yields on capital that frequently outperform traditional savings vehicles.
A user can lock digital assets into a decentralized lending protocol, making those funds immediately available to global borrowers, and earn interest generated directly by the underlying code. However, navigating this decentralized frontier requires a high level of digital literacy, as the absence of central intermediaries means consumers must take absolute responsibility for their own security, private keys, and risk management.
The Critical Need for Advanced Digital Financial Literacy
As financial tools become more sophisticated, the gap between the financially literate and the digitally excluded risks widening. Managing money in a digital-first world demands a secondary layer of education that blends core economic principles with digital safety and technological competence.
-
Understanding Algorithmic Bias: Consumers must recognize that the automated recommendations provided by financial apps are driven by underlying code that may prioritize vendor profitability over user benefit.
-
Managing Digital Security Perimeters: With financial data distributed across multiple apps and cloud services, individuals must master identity protection, utilizing hardware-based multi-factor authentication and encrypted password managers to protect assets from cyber criminals.
-
Evaluating Complex Alternative Assets: The proliferation of digital tokens, fractional real estate platforms, and crowdfunded equity requires modern investors to perform due diligence on non-traditional asset classes that lack standard regulatory backstops.
Frequently Asked Questions
What happens to my digital financial assets if a fintech company goes out of business?
Most reputable fintech companies partner with traditional, chartered banks to hold customer deposits. While the fintech company provides the digital interface, your actual money resides in an account that is insured by the Federal Deposit Insurance Corporation up to two hundred fifty thousand dollars. If the fintech app ceases operations, your core funds remain protected and accessible through the underlying partner institution, though it is vital to read the terms of service to verify this arrangement before depositing funds.
How does the transition to a cashless society impact low-income individuals?
A completely digital financial ecosystem can inadvertently marginalize unbanked or underbanked populations who rely on cash due to a lack of traditional identification, stable internet access, or smartphone technology. To prevent financial exclusion, many local and state governments have enacted legislation requiring brick-and-mortar retail businesses to continue accepting physical cash currency as a valid form of payment for goods and services.
Can artificial intelligence financial advisors fully replace human certified financial planners?
Artificial intelligence excels at data aggregation, pattern recognition, tax-loss harvesting, and executing programmatic savings routines. However, AI cannot replicate the emotional intelligence, nuanced life-stage coaching, and behavioral guardrails provided by a human advisor. A human professional remains essential for navigating complex family dynamics, managing emotional market panic, and tailoring estate planning to highly subjective personal values.
What is the security risk of linking multiple accounts to a single financial dashboard app?
The primary risk is creating a single point of failure. If an unauthorized actor gains access to your master dashboard credentials, they can view your complete financial picture, including account numbers, balances, and liabilities across all linked institutions. To mitigate this risk, choose aggregators that use read-only tokens, meaning the app can view your data but cannot initiate outbound transfers, and enforce strict biometrics on your device.
How do modern Buy Now Pay Later services differ from traditional credit card debt?
Buy Now Pay Later services typically split a single purchase into four equal, interest-free installments paid over a short period, often six weeks. Unlike credit cards, they rarely require a hard credit inquiry, making them highly accessible. However, if an installment is missed, substantial late fees trigger, and some providers convert the remaining balance into high-interest loans, creating an entry point into debt cycles for consumers who treat these services as a extension of disposable income.
Will Central Bank Digital Currencies replace traditional commercial bank accounts?
Central Bank Digital Currencies are digital forms of fiat currency issued directly by a nation central bank. While they could streamline wholesale clearing and government benefit distributions, they are unlikely to completely eliminate commercial banks. Commercial institutions play a vital role in local credit creation, underwriting mortgages, and providing consumer-facing customer service, functions that central banks are not structured or staffed to manage directly.
To gain a broader perspective on the systemic changes taking place within the financial services industry, watch this panel discussion on AI and the Future of Digital Transformation, which explores how emerging policies and shifting technologies are actively reshaping global market systems.